Debt Management for Migrant Workers: How toReduce Loans and Personal Debt

iSavta | 02.10.2026
Working overseas can provide a better income and help migrant workers support their families. But earningmoney abroad does not always mean having financial freedom. Many migrant workers have loans, creditcard balances, family debts, or money borrowed to cover recruitment, travel, housing, education, or otherexpenses.
When several debts are combined with regular family expenses, it can feel difficult to make progress.
The good news is that debt can be managed. With a clear plan, careful spending, and consistent payments, migrant workers can reduce their debt and work toward becoming financially independent.
Understand Exactly How Much You Owe
Before trying to pay off debt, you need to know exactly what you owe.
Make a simple list of every loan or debt, including:
Total amount owed
Monthly payment
Interest rate
Payment due date
Remaining repayment period
Any late fees or penalties
Include debts in both your host country and your home country if you have them.
It can be uncomfortable to see the total amount written down, but knowing the full picture is the first steptoward taking control of your finances.
Separate Necessary Expenses From Debt Payments
Your salary has to cover more than loan payments.
As a migrant worker, you may need money for food, transportation, phone bills, personal expenses, andother necessities. You may also send money home to support your family.
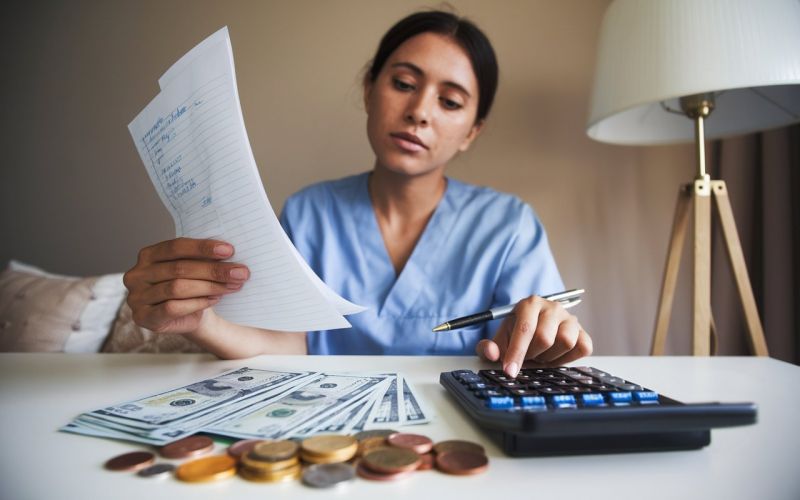
Before deciding how much extra money you can put toward debt, calculate your essential monthlyexpenses.
A simple budget can show you how much money is actually available for debt repayment.
Do not create a repayment plan that leaves you without enough money for basic needs.
Prioritize Your Debts
If you have several debts, you need to decide which ones to focus on first.
One common strategy is the debt avalanche method. With this approach, you continue making therequired payments on all debts while putting extra money toward the debt with the highest interest rate.
Once that debt is paid off, you put the extra money toward the next highest-interest debt.
This approach can reduce the amount of interest you pay over time.
Another approach is the debt snowball method, where you focus on paying off your smallest debt first.This can provide a psychological boost because you see debts disappear sooner.
The best method is one you can realistically follow consistently.
Avoid Taking New Debt to Pay Old Debt
It can be tempting to take another loan when you are struggling with existing payments.
Sometimes refinancing or consolidating debt can be appropriate, but taking a new high-interest loan simplyto cover an old one can make the problem worse.
Before borrowing more money, ask yourself:
Will this actually reduce my debt, or am I only moving the debt somewhere else?
Understand the interest rate, fees, repayment period, and total amount you will eventually pay.
Never accept a loan simply because the monthly payment looks small. A longer repayment period cansometimes mean paying much more interest overall.
Be Careful With Credit Cards
Credit cards can make everyday purchases convenient, but carrying a balance can become expensive wheninterest and fees accumulate.
If you are trying to reduce debt, consider limiting unnecessary credit card purchases.
Whenever possible, pay more than the minimum required payment. Minimum payments can keep anaccount in good standing, but they may take a long time to eliminate the balance.
If you cannot afford to pay the full balance, focus on reducing the amount you owe and avoid adding unnecessary new charges.
Create a Realistic Monthly Budget
A budget does not have to be complicated.
Write down your monthly income and divide your expenses into categories such as:
Essential expenses: Food, housing, transportation, utilities, and other necessities.
Family support: Money regularly sent to children, parents, or other family members.
Debt payments: Required loan and credit payments.
Personal spending: Clothing, entertainment, eating out, and other non-essential expenses.
Savings: Money set aside for emergencies or future goals.
Look for expenses that can be reduced without making your life unnecessarily difficult.
Even a small amount saved every month can become significant when consistently directed toward debt.
Set a Specific Debt-Payment Goal
Instead of simply saying, "I want to pay off my debt," set a specific goal.
For example:
"I will pay an extra amount toward my highest-interest loan every month."
Or:
"I will pay off my smallest debt within the next six months."
A specific goal makes it easier to track your progress.
Keep a record of your remaining balances. Watching the amount decrease can provide motivation tocontinue.
Talk to Your Lenders if You Are Struggling
If you are having difficulty making payments, do not simply ignore the problem.
Contact your lender before you miss payments and ask whether there are available options. Depending onthe lender and your circumstances, there may be ways to restructure payments, change the repaymentschedule, or discuss other arrangements.
Ignoring debt can lead to additional interest, penalties, collection activity, and damage to your financialsituation.
If you are dealing with a large amount of debt, consider seeking advice from a qualified financial counseloror appropriate financial institution.
Be Careful About Sending Too Much Money Home
Supporting your family is one of the main reasons many people work overseas.
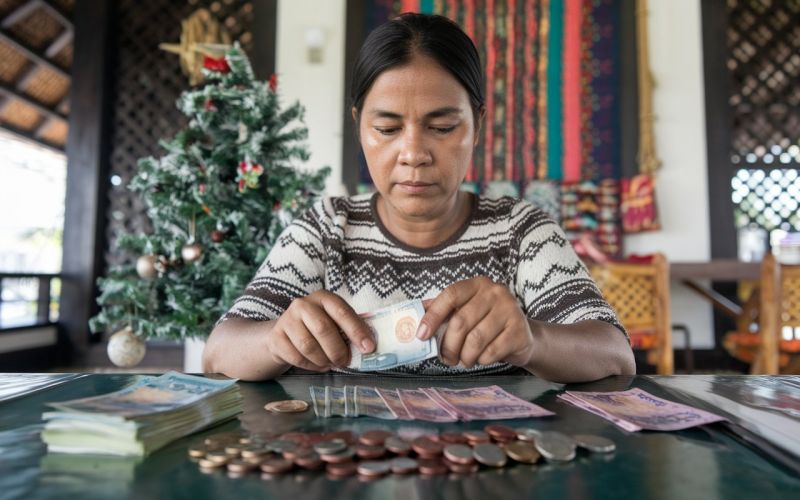
However, sending every available peso or shekel home while keeping nothing for yourself can make itdifficult to deal with emergencies or repay debt.
Talk openly with your family about your financial situation.
If possible, agree on a realistic monthly amount that can be sent home while still allowing you to cover yourexpenses, repay debt, and build some savings.
Remember that your financial stability also benefits your family in the long term.
Build a Small Emergency Fund
When you are focused on paying off debt, saving money may seem impossible.
However, having at least a small emergency fund can help prevent you from taking on new debt whensomething unexpected happens.
An emergency could include an urgent trip home, unexpected personal expenses, medical needs, or atemporary loss of income.
Even setting aside a small amount regularly can provide some financial protection.
Once your high-interest debt is under control, you can work toward building a larger emergency fund.
Avoid "Get-Rich-Quick" Solutions
When debt becomes stressful, promises of quick money can be especially tempting.
Be careful with investment opportunities, online businesses, cryptocurrency schemes, gambling, or anyonepromising guaranteed profits.
If someone tells you that you can quickly double your money with little or no risk, be extremely cautious.
The fastest way out of debt is usually not another risky financial opportunity. It is a realistic plan thatreduces what you owe while preventing new debt.
Your Salary Is the Result of Your Hard Work
For migrant workers, every paycheck represents time spent away from family and the effort required towork in another country.
Managing debt means making sure that as much of that hard-earned money as possible goes towardbuilding a more secure future.
You do not need to eliminate all your debt overnight.
Start by understanding what you owe. Create a realistic budget. Prioritize your debts. Avoid unnecessaryborrowing. Make consistent payments and track your progress.
Most importantly, do not be ashamed of having debt. Financial problems can happen to anyone.
What matters is taking control of the situation and having a plan.
With patience and discipline, you can gradually reduce your debts, increase your financial stability, andeventually reach the point where more of your hard-earned income belongs to you and your family's future.